What to Include on an Invoice: 12 Fields Every Invoice Needs
What to include on an invoice: the 12 fields every invoice needs, the extra details UK and EU VAT law adds, what the IRS expects and a layout to copy.
Knowing what to include on an invoice is the difference between getting paid promptly and answering questions from a confused client. A complete invoice lets an accounts payable team match it to a purchase and approve it without coming back to you, and it gives you a record you can rely on later.
This checklist covers the 12 fields every invoice should carry, then what the law adds in the UK and EU, and what US federal tax guidance does and does not say. If you want the result on one page, skip to the fill-in invoice layout or start from a free invoice template. For the full country-by-country rules, see the UK invoice requirements and the other country guides linked below.
The 12-field invoice checklist
What must every invoice include? At minimum: your business name and contact details, the client's name and address, a unique invoice number, the invoice date, the date of supply, a description of what you supplied, quantities and prices, the subtotal, any tax, the total due, the due date and payment instructions. VAT-registered sellers must add further details.
| # | Field | Why it matters |
|---|---|---|
| 1 | Your business name, address and contact details | Tells the client who to pay and where to send questions |
| 2 | Client's name and billing address | Gets the invoice to the right legal entity and AP team |
| 3 | Unique invoice number | Lets both sides find, match and reference the invoice |
| 4 | Invoice date | Starts the payment terms and dates the record |
| 5 | Date of supply (when the work was done or goods delivered) | Required on UK invoices; needed for VAT timing |
| 6 | Description of goods or services | Lets the client check the bill against what was agreed |
| 7 | Quantity and unit price for each line | Shows how each amount was worked out |
| 8 | Line amounts and subtotal | Quantity × unit price, summed |
| 9 | Tax rate and tax amount, if you charge tax | Required on VAT invoices; shows the client what is tax |
| 10 | Total amount due, with the currency | The number the client actually pays |
| 11 | Due date or payment terms | Without one, "when" is open to interpretation |
| 12 | Payment instructions | Removes the last excuse for a late payment |
The sections below explain each group of fields.
1. Your business information
Place this prominently at the top of every invoice:
- Business name (your legal name, or a trading name with your legal name where your local rules require it)
- Address
- Email address for invoice questions
- Phone number (optional)
- Tax registration number, where you have one and your tax authority requires it on invoices, such as a UK or EU VAT number
- Logo (optional)
In the UK, GOV.UK's guidance on what invoices must include adds rules on names: a sole trader using a business name must also show their own name and an address where legal documents can be delivered, and a limited company must show its full name as it appears on its certificate of incorporation. A VAT number is only required if you are VAT-registered; HMRC's VAT invoice rules are covered below.
2. Client information
- Client's full business name (the legal entity, not just a contact person)
- Client's billing address
- Client's email address
- Client's VAT number, where the law requires it (in the EU, mainly when the customer accounts for the VAT under the reverse charge or receives an intra-EU supply of goods; see the EU section below)
- Attention line (the person or department handling payment, if known)
An invoice addressed to the wrong entity or department can be sent back or sit unapproved, which delays payment.
3. Invoice identification
- Invoice number: a unique identifier you never reuse. UK and EU VAT invoices need a sequential number; US federal tax law sets no numbering rule, but your client's AP system will still match your payment by it. See invoice numbering systems for how to set one up and invoice number best practices for handling gaps and corrections.
- Invoice date: the date you issue the invoice.
- Date of supply: when you delivered the goods or finished the service, if different from the invoice date.
- Due date: when payment is expected. Common terms include Net 15, Net 30 and Due on Receipt. Read more about payment terms to choose one.
- Purchase order number, if the client gave you one. Many corporate clients cannot approve an invoice without it, so ask before you invoice.
- Project or reference number, which ties the invoice to a contract or job.
4. Itemized line items
This is the core of your invoice. Each line should include:
| Column | Description | Example |
|---|---|---|
| Description | Clear, specific description of the service or product | "Website redesign: homepage and 3 landing pages" |
| Quantity | Number of units, hours or items | 1 |
| Unit price | Rate per unit | $3,500.00 |
| Amount | Quantity × unit price | $3,500.00 |
Best practices for line items:
- Be specific. "Consulting services" is vague. "Brand strategy consulting: Q1 2026 market positioning" is clear.
- Break large projects into meaningful phases or deliverables.
- Match descriptions to what was agreed in the contract or scope of work.
- Use consistent units (hours, days, flat fee) across line items.
If you're not sure how to structure your line items, our guide on how to write an invoice walks through examples.
5. Financial summary
Below your line items, show:
- Subtotal: the sum of all line items before tax
- Discount, if any, with the reason (for example "Early payment discount 2%")
- Tax amount, with the rate stated (for example "VAT 20%" or "Sales tax 8.5%")
- Shipping or delivery charges, if any
- Total amount due, displayed prominently, with the currency
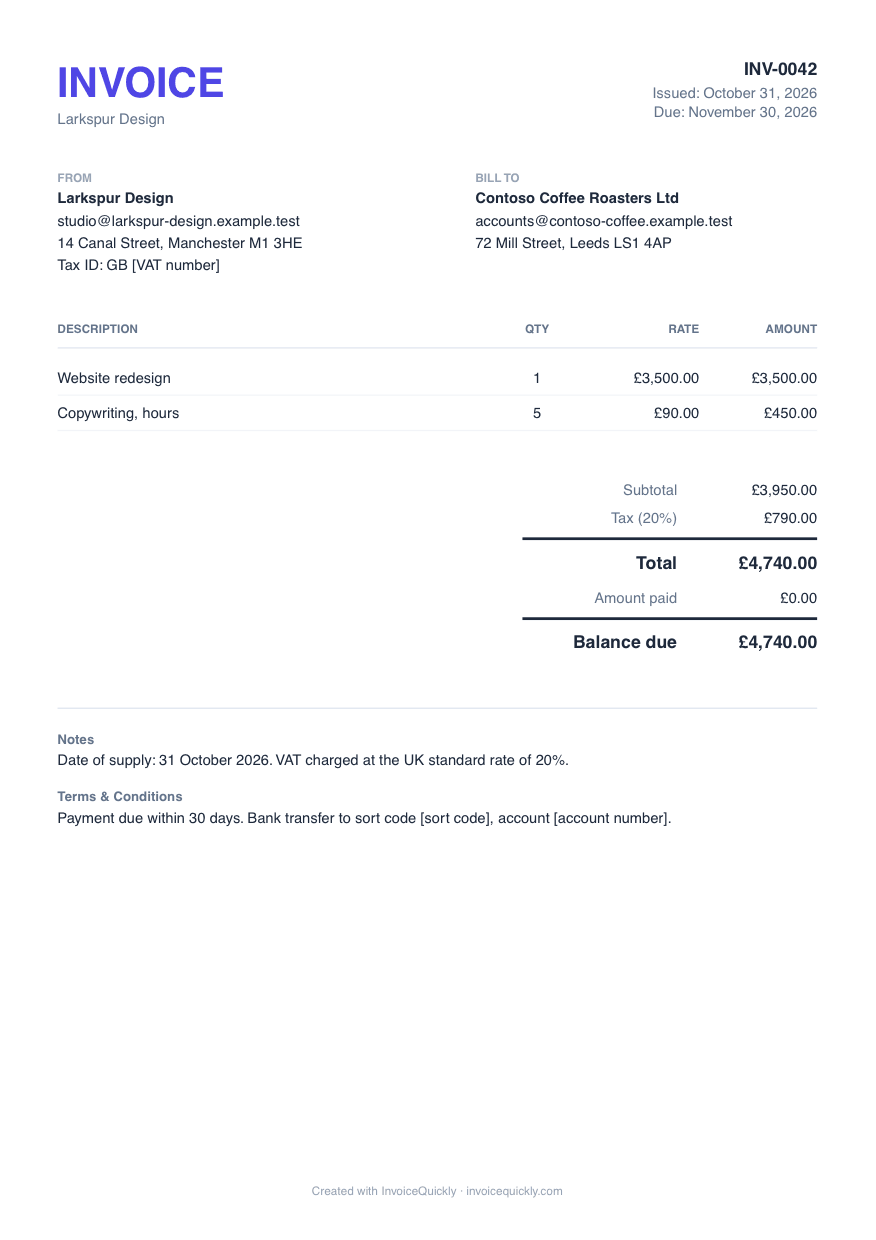
Worked example (UK, VAT-registered designer):
| Line | Calculation | Amount |
|---|---|---|
| Website redesign | 1 × £3,500.00 | £3,500.00 |
| Copywriting | 5 hours × £90.00 | £450.00 |
| Subtotal (excluding VAT) | £3,500.00 + £450.00 | £3,950.00 |
| VAT at 20% | £3,950.00 × 0.20 | £790.00 |
| Total due | £3,950.00 + £790.00 | £4,740.00 |
The 20% figure is the UK standard rate (GOV.UK: VAT rates). A seller who is not VAT-registered would show a total of £3,950.00 and no VAT line.
6. Payment instructions
This section directly affects how quickly you get paid. Include:
- Accepted payment methods (bank transfer, card, PayPal, check)
- Bank details (account name, bank name, account number, routing number or sort code, and SWIFT/BIC or IBAN for international transfers)
- Online payment link, if you use a payment provider such as Stripe or PayPal
- Payment terms (Net 30, Due on Receipt and so on)
- Late payment policy, if your contract and local law allow one (for example "A late fee of 1.5% per month applies to overdue balances"). Rules differ by state and country: see late fee laws by state, and use the late fee calculator to see what a rate means in money.
- Currency, especially for international clients
7. Additional notes and terms
- Scope of work summary (a brief reminder of what was delivered)
- Thank-you note
- Terms and conditions (warranty, refund policy, ownership transfer)
- Any statement your tax rules require, such as a reverse charge note on an EU cross-border invoice
What does the law require, by region?
Requirements depend on where you are and whether you are registered for VAT or GST. This table summarizes the official sources; follow the links for the full rules. Last reviewed 28 October 2026.
| Region | What the official source says | Source |
|---|---|---|
| United States (federal) | No federal list of invoice fields and no numbering rule. The IRS says to keep supporting documents that show the amounts and sources of your gross receipts, and lists invoices among them. State sales tax rules can add requirements. | IRS: What kind of records should I keep |
| UK, all businesses | A unique identification number, your name, address and contact details, the customer's name and address, a description, the supply date, the invoice date, the amounts charged, VAT if applicable and the total owed. | GOV.UK: Invoices, what they must include |
| UK, VAT invoices | A sequential number, the time of supply, the issue date if different, your name, address and VAT number, the customer's name and address, a description, and for each line the quantity, unit price, VAT rate and amount excluding VAT, plus the total excluding VAT, any cash discount rate and the total VAT in sterling. A simplified invoice is allowed for supplies of £250 or less. | HMRC VAT Notice 700, section 16 |
| EU, VAT invoices | Article 226 of the VAT Directive lists the date of issue, a sequential number in one or more series, the seller's VAT number, the customer's VAT number where the customer is liable for the VAT or receives an intra-EU supply of goods, both full names and addresses, the quantity and nature of what was supplied, the supply date where it differs, the taxable amount per rate, the unit price excluding VAT, the VAT rate and the VAT amount payable. Member states apply it through national law. | Council Directive 2006/112/EC, Article 226 |
| Other countries | Rules differ. See our reviewed guides for Australia, Canada and the UK in more depth. | Each guide cites its tax authority |
If you are registered for VAT or GST, the difference between a tax invoice and an ordinary one matters; see tax invoice vs regular invoice. This is general information, not legal or tax advice; check with your tax authority or an adviser for your situation.
Common mistakes that delay payment
- Missing or incorrect PO numbers. Corporate clients often can't approve an invoice without a matching purchase order. Ask for the PO number before invoicing.
- Vague descriptions. "Services rendered" invites questions. Say what was delivered.
- Wrong client entity. Invoicing "John" instead of "Smith Corp Ltd" can get your invoice rejected by accounts payable.
- No due date. Without a due date, the client decides when to pay. Always state the date or the terms.
- Missing tax details. A VAT-registered customer needs a valid VAT invoice to reclaim the VAT, so a missing VAT number or rate usually means a request for a corrected invoice.
A fill-in invoice layout with every field
You can build invoices from a template or in software. InvoiceQuickly can draft the client, line items, rates and terms from a typed or spoken description into an editable invoice that you review before saving (the Free plan includes 5 invoices and 3 AI drafts). Its PDF shows your business details, the invoice number, issue and due dates, the client's details, line items, subtotal, one discount line, one tax line, the total, any recorded payments and the balance due, and your notes and terms. New invoices print the tax ID saved in your business settings and the tax ID saved on the client, such as a VAT number. Invoices created before you saved a tax ID keep their original details. There is no separate PO or supply-date field, so put the PO number and supply date in the notes if your client or tax rules need them.
If you prefer to build invoices yourself, use this structure:
[Your Logo]
[Business Name]
[Address, Email, Phone, VAT number if registered]

INVOICE
Invoice #: [Number]
Invoice date: [Issue date]
Date of supply: [If different]
Due: [Due date]
PO #: [If applicable]

Bill To:
[Client legal name]
[Client address]
[Client email, VAT number if required]

| Description | Qty | Rate | Amount |
|-------------|-----|------|--------|
| [Item 1]    |  1  | $X   | $X     |
| [Item 2]    |  5  | $Y   | $5Y    |

                        Subtotal: $XX
                        Tax (X%): $XX
                        Total Due: $XX

Payment: [Methods and bank details]
Terms: [Net 30 / Due on Receipt / etc.]
Notes: [Thank you, T&Cs, required tax statements]
Next steps
Once the invoice is complete, delivery matters too. Read our guide on how to send an invoice by email for subject lines and message templates.
Practical guidance for freelancers and small businesses creating and managing invoices.
Create your next invoice from one prompt
Describe the client, work, prices, and payment terms. Review every field before you send.
Create a Free InvoiceRelated guides
How to Invoice International Clients: Currency and Tax
Invoice clients abroad with fewer surprises: currency and fees, tax IDs, reverse charge, withholding, e-invoicing countries and a cross-border checklist.
Tax Invoice vs Regular Invoice: UK, Australia, NZ, US
A tax invoice lets a VAT- or GST-registered buyer claim back tax; a regular invoice only asks for payment. UK, Australian, NZ and US rules side by side.
End-of-Year Invoicing Checklist: Close Your Books Right
Year-end invoicing checklist: billing cutoffs, unbilled work, credit notes, W-9s and the 2026 Form 1099-NEC changes, so December revenue is right.
VAT Invoicing Guide: EU Rules, Reverse Charge and Exports
VAT invoices for cross-border sales: EU Article 226 fields compared with HMRC rules, reverse charge wording, EU rates, OSS and invoice deadlines.
Useful, occasional notes
Get invoicing tips that actually help
Join the InvoiceQuickly update list for practical invoicing advice and product news.
No spam, ever. Unsubscribe anytime.